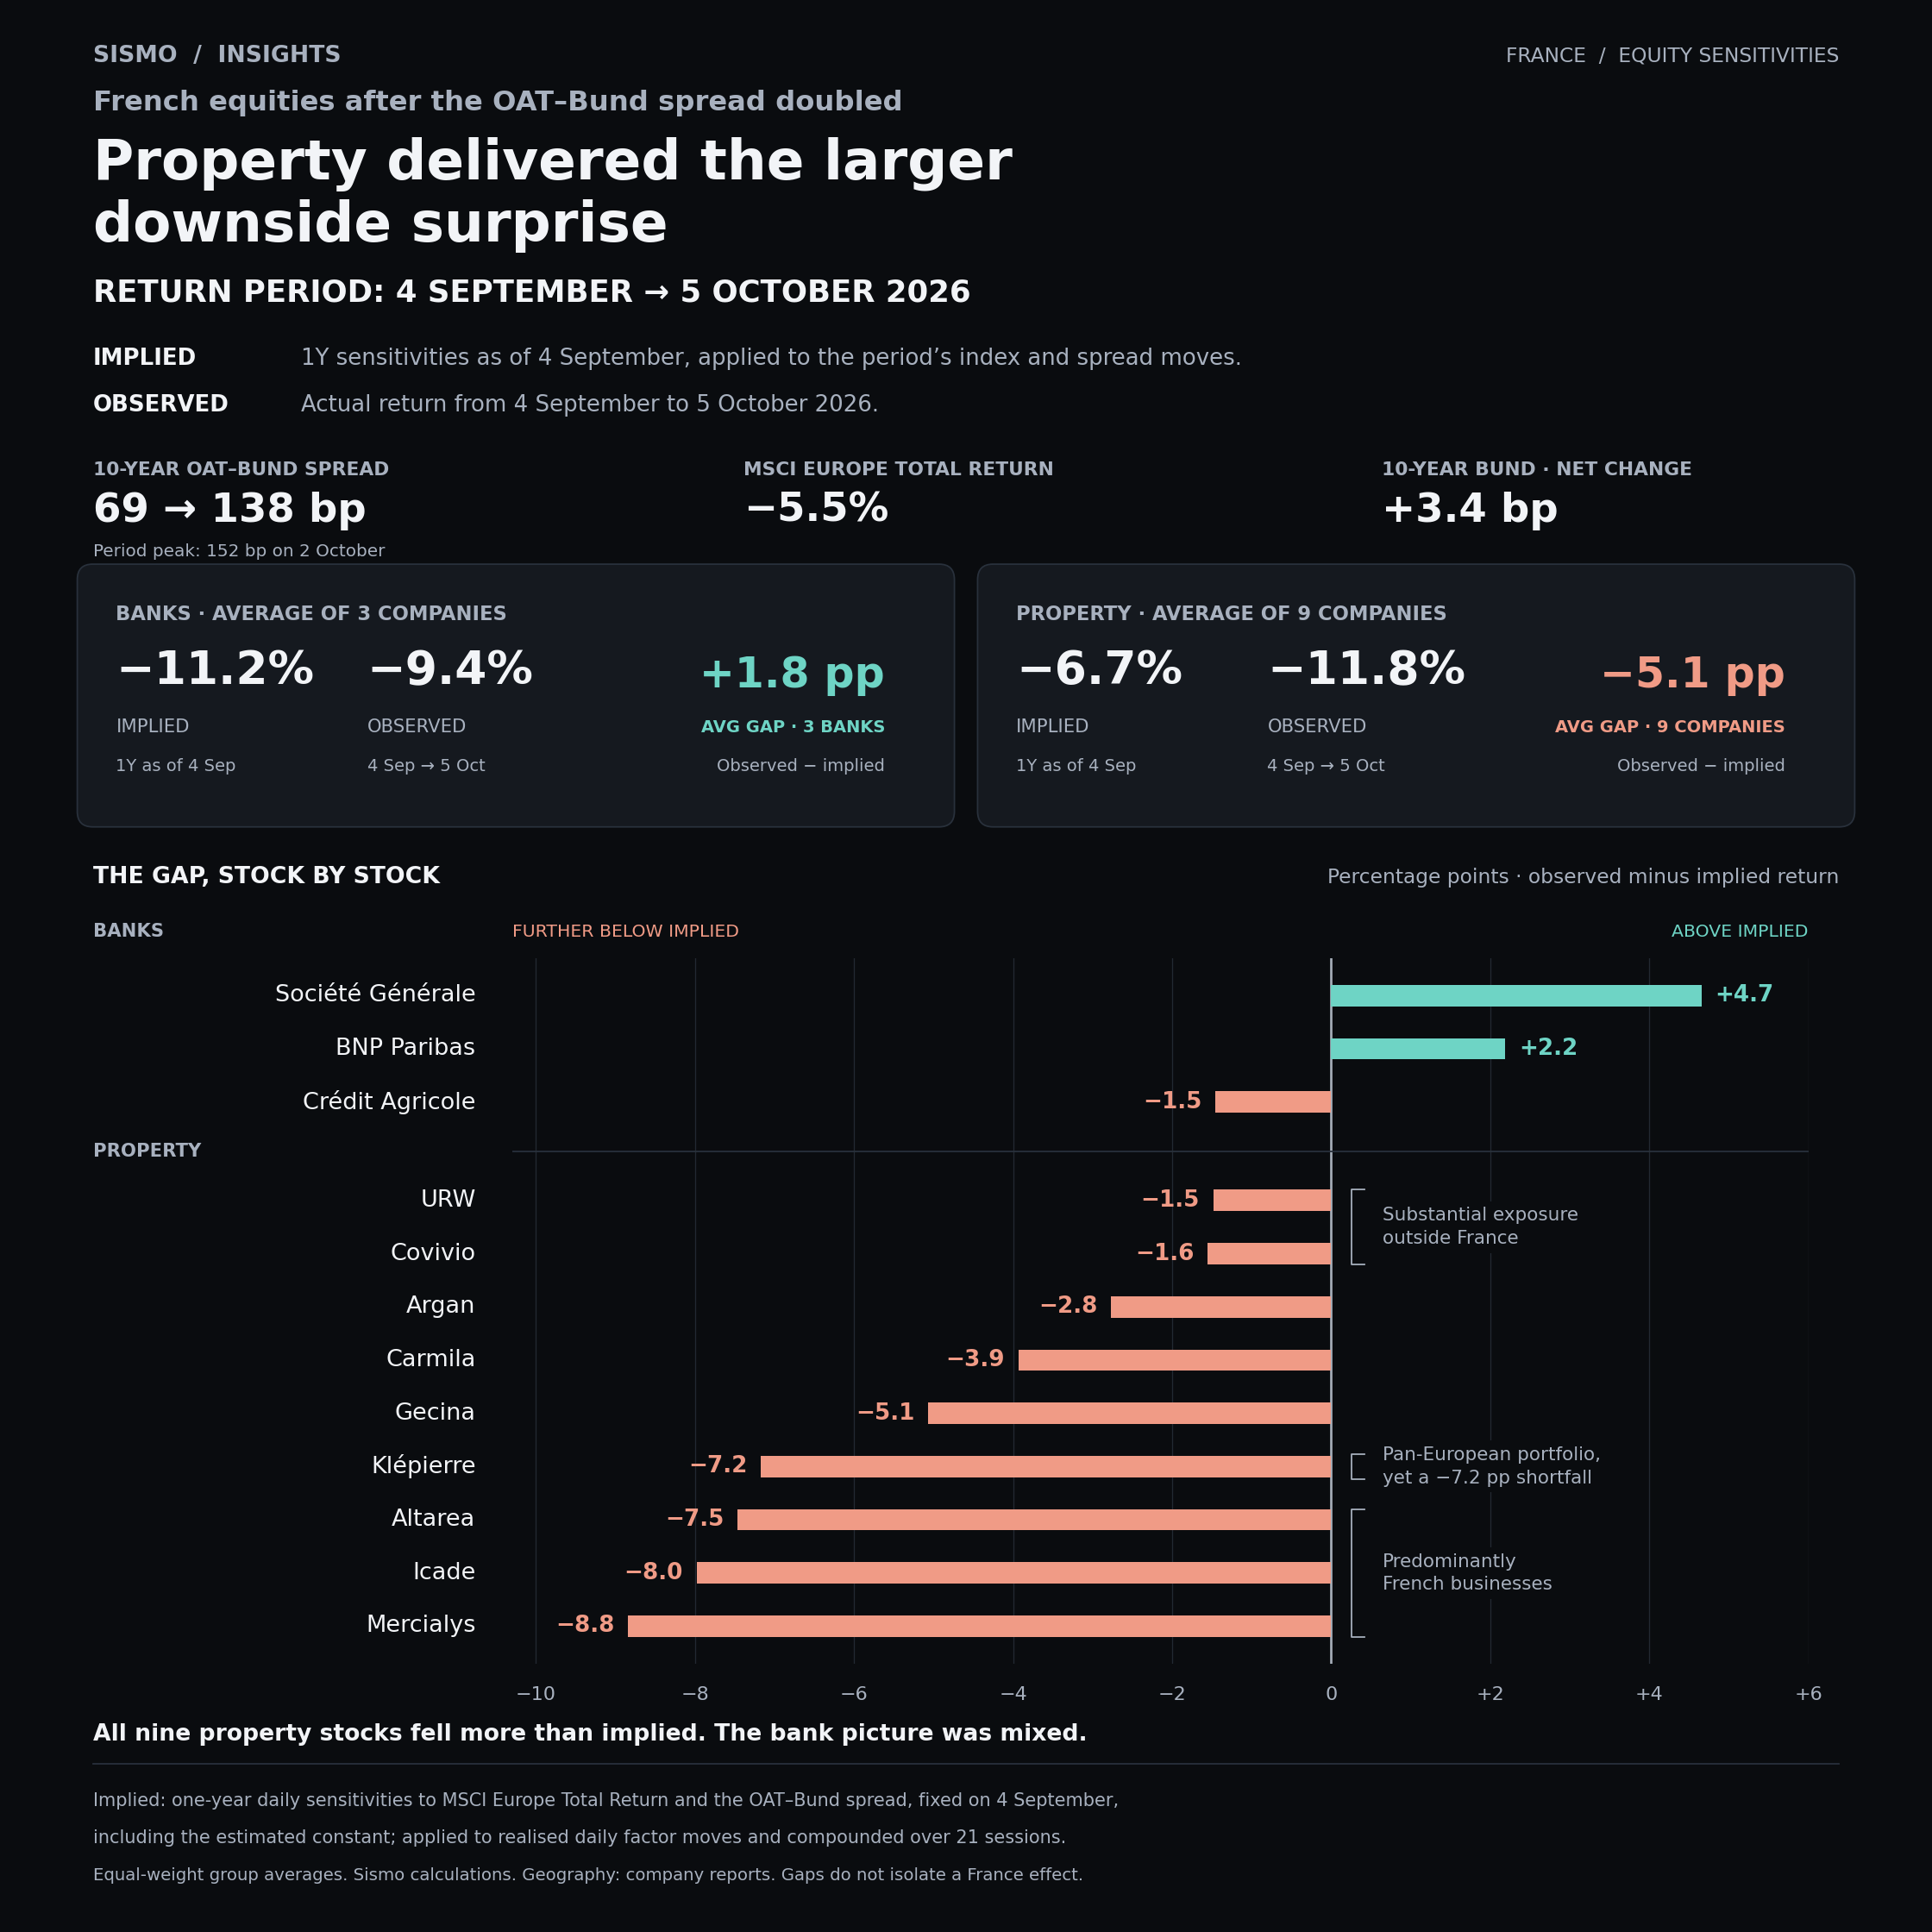
When the OAT–Bund spread doubled over September and early October, French banks fell less, on average, than their earlier sensitivities implied. Listed property companies fell substantially more - and all nine in our sample underperformed their estimates.
Between 4 September and 5 October 2026, the 10-year spread widened from 69 to 138 basis points, after peaking near 152 on 2 October. The move unfolded against France’s budget debate: the government presented its 2027 budget on 1 October, including €43 billion of measures. Over our window, the Bund yield rose just 3.4 basis points. Almost all of the roughly 72-basis-point rise in French yields therefore came from the wider spread.
Why focus on banks and property? Sovereign stress can reach banks through funding costs, bond holdings and weaker borrowers. Property companies face refinancing costs and pressure on asset valuations. The ECB documents both the bank–sovereign link and the property financing channel.
What did sensitivities measured on 4 September imply, given the subsequent spread widening and 5.5% fall in MSCI Europe Total Return?
Banks performed 1.8 percentage points better than implied, on average. But the picture was mixed: Société Générale and BNP Paribas exceeded their estimates, while Crédit Agricole fell 1.5 points short. This suggests some resilience relative to the sensitivity baseline, despite a larger fall than the European index.
Property is the clearer result. Its implied −6.7% return was only modestly worse than the index’s −5.5%. The observed loss was −11.8%, with every company falling short - by 5.1 points on average.
The stock-level pattern offers a clue. The smallest shortfalls came from URW (−1.5 points) and Covivio (−1.6), both with substantial portfolios outside France. The largest came from French-focused Mercialys, Icade and Altarea. That is consistent with domestic exposure contributing to the surprise. Yet pan-European Klépierre missed by 7.2 points: geography alone cannot explain the pattern.
For a portfolio manager, the useful distinction is between losses broadly consistent with historical sensitivities and losses that require further explanation. Banks held up somewhat better than the baseline; property underperformed it across all nine companies. That breadth warrants a review of domestic demand, refinancing and company-specific developments. The shortfall alone does not establish mispricing or predict a rebound.
Method: Sismo calculations using one-year daily sensitivities to MSCI Europe Total Return and changes in the France–Germany 10-year government-yield spread, fixed on 4 September. The same total-return index is used for estimation and implied returns. Implied daily returns include the estimated constant and realised index and spread moves, compounded over 21 sessions. Observed stock returns include dividends; group figures are equal-weight averages. All spread levels, including the 152 bp peak, come from Sismo’s daily series and are rounded.
The constant adds about 0.7 percentage points to implied bank returns and subtracts about 0.35 points from property returns. Excluding it widens the gaps to +2.5 and −5.5 points respectively, without changing either conclusion. Calculations use unrounded figures.