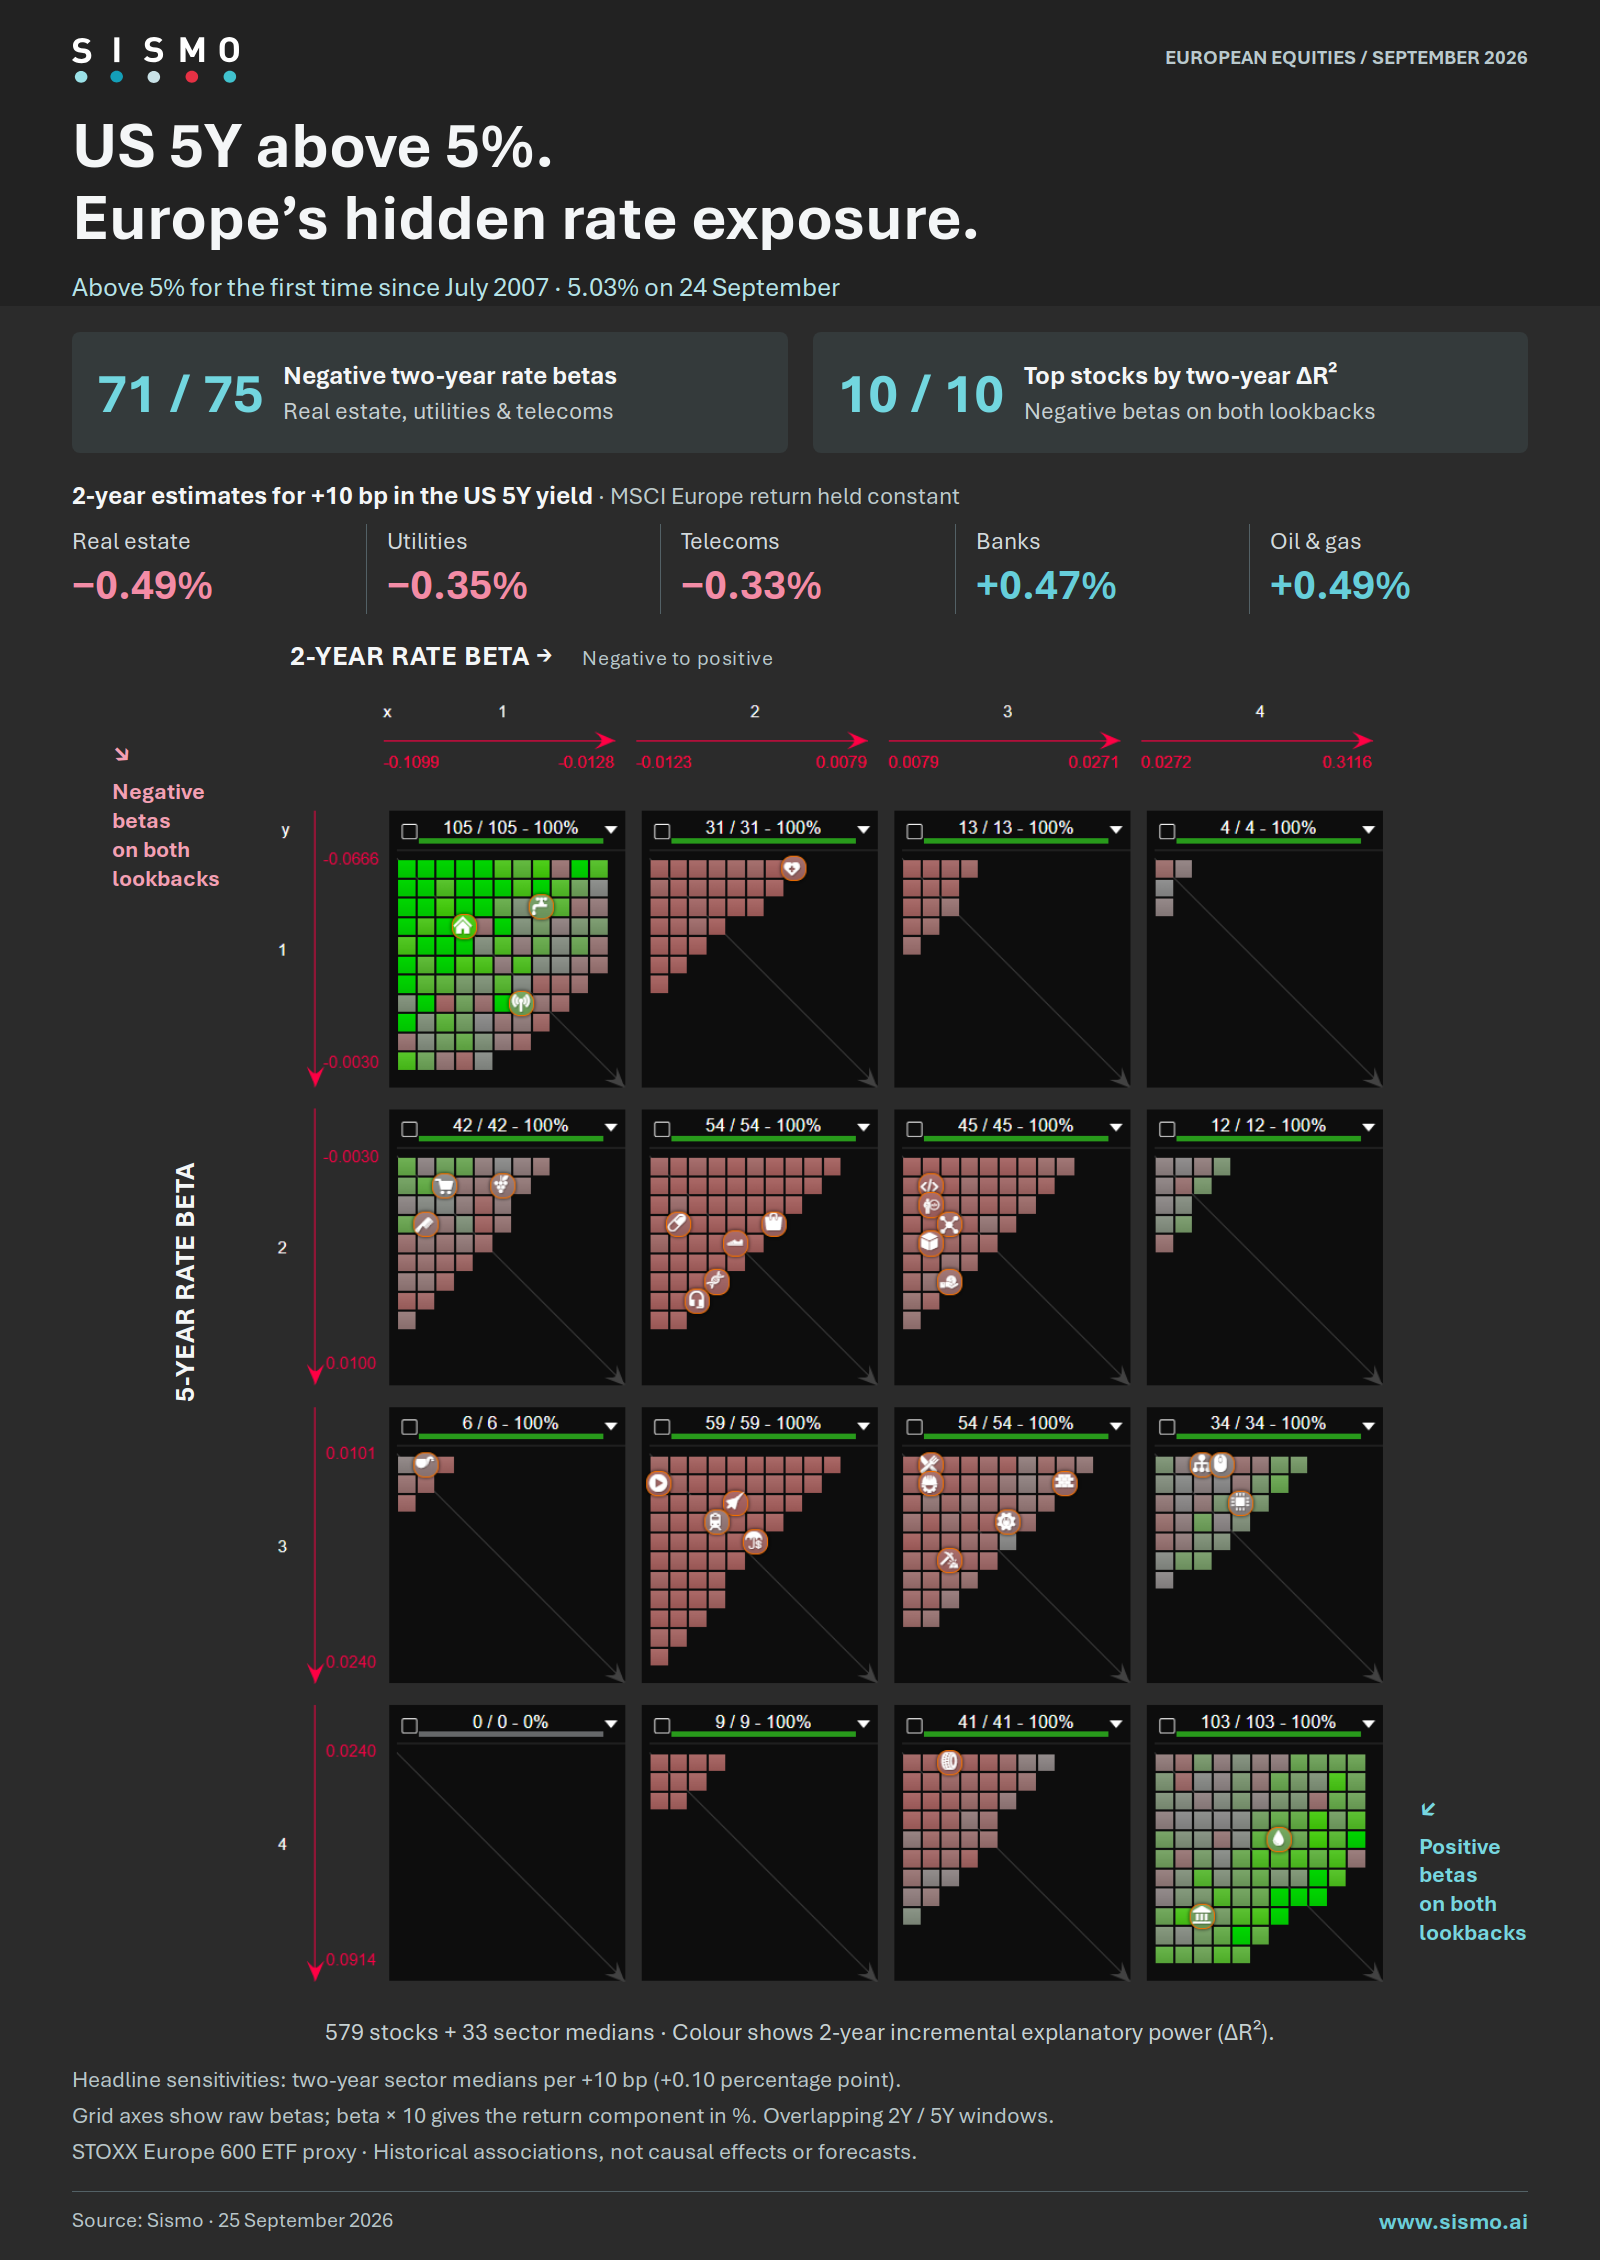
The US five-year Treasury yield moved above 5% in the week of 21 September 2026, for the first time since July 2007, closing at 5.03% on 24 September.
What would a further 10 bp rise in the US five-year yield imply for European equities, holding the broad market return constant? Sismo’s macro betas translate that scenario into estimated stock-level sensitivities, conditional on MSCI Europe returns.
In our European equity sample, 71 of 75 stocks across real estate, utilities and telecoms have negative two-year rate betas, after controlling for MSCI Europe. The ten stocks for which rates add the most explanatory power also have negative betas on both the two- and five-year lookbacks.
The analysis uses a STOXX Europe 600 ETF holdings proxy as of Friday, 25 September 2026. The two-year analysis covers 596 stocks; requiring five years of stock-price history leaves a common sample of 579 stocks across 33 Sismo sectors. All figures below use that common sample. Each daily regression combines changes in the US five-year Treasury yield with MSCI Europe returns.
Three sectors, a common exposure
Negative two-year rate betas appear in all 27 real estate stocks, 29 of 32 utilities and 15 of 16 telecoms in the common sample.
For a +10 bp change in the US five-year yield, the sector-median two-year coefficients correspond to estimated return components of −0.49% for real estate, −0.35% for utilities and −0.33% for telecoms, with the index return held constant.
All three sectors also have negative five-year medians, although the telecom median is close to zero: −0.03% per +10 bp, compared with −0.33% over two years. The two estimation windows overlap, so this comparison highlights lookback sensitivity rather than a change between two separate periods.
A portfolio spread across these sectors may therefore hold several expressions of the same rate exposure. Its aggregate sensitivity depends on the individual stocks and their weights.
Where rates add the most information
The ten highest two-year ΔR² values all belong to stocks with negative rate betas on both lookbacks: five in real estate, four in utilities and one in telecoms.
- 1Real estate
- 2Utilities
- 3Telecoms
- 4Food & drug retail
- 5Banks
- 6Oil & gas
- 7Tech hardware
- 8Semiconductors
Beyond the index-only model, rates explain an additional 8.78% of total return variance for LEG Immobilien, 8.38% for Vonovia and 7.68% for TAG Immobilien. Their two-year coefficients imply estimated return components of −0.98%, −1.01% and −1.10%, respectively, for +10 bp, holding the index return constant.
| Company | Sector | 2Y estimate | 5Y estimate | 2Y ΔR² (%) |
|---|---|---|---|---|
| LEG Immobilien | Real Estate | −0.98% | −0.55% | 8.78 |
| Vonovia | Real Estate | −1.01% | −0.56% | 8.38 |
| TAG Immobilien | Real Estate | −1.10% | −0.67% | 7.68 |
| Severn Trent | Utilities | −0.75% | −0.47% | 7.31 |
| National Grid | Utilities | −0.66% | −0.38% | 7.13 |
| United Utilities | Utilities | −0.71% | −0.44% | 6.38 |
| Terna | Utilities | −0.49% | −0.33% | 5.66 |
| Balder | Real Estate | −0.79% | −0.61% | 5.53 |
| Castellum | Real Estate | −0.67% | −0.46% | 5.05 |
| Cellnex | Telecoms | −0.75% | −0.57% | 5.04 |
Estimates are return components for a +10 bp yield change, with the index return held constant. Ranked by two-year ΔR² within the 579-stock common sample.
Interpreting the sector differences
Financing costs, bank margins and exposure to the economic cycle offer possible explanations for these sector differences. The regression does not identify which channel drives each coefficient. 1
Real estate, utilities and telecoms: financing costs and valuation. Negative sensitivities are consistent with debt-funded assets, recurring investment needs and the valuation of long-lived cash flows. Higher rates can affect future refinancing costs and required equity returns. The ECB’s May 2026 review identifies property markets as sensitive to medium- and long-term interest rates. 2
Current interest expense need not rise immediately. National Grid reports that around 80% of its debt has fixed interest rates, alongside regulatory mechanisms for recovering debt costs. Cellnex reports around 77% fixed-rate borrowing, with an average maturity of 4.1 years at end-2025. These examples illustrate why debt maturities, hedging and regulation matter: an equity valuation can reflect future financing conditions even while current borrowing costs are largely protected. They do not establish the cause of the observed betas. 3 4
Banks: asset yields versus funding costs. The sector-median estimate is +0.47% per +10 bp over two years, compared with +0.46% over five years. A positive sensitivity is consistent with lending and reinvestment yields rising faster than deposit costs. The ECB’s May 2026 review supports this mechanism, while highlighting the influence of the yield curve, deposit competition and loan demand. The US five-year yield remains a macro indicator here, not a direct measure of European lending margins. 2
Oil & gas: a possible shared demand or inflation driver. The sector-median estimate is +0.49% per +10 bp over two years, compared with +0.44% over five years. Stronger demand or higher energy prices can support producers’ earnings while lifting inflation expectations and nominal yields. That is a plausible common driver of a positive beta. It should not be confused with a benefit from monetary tightening: IMF research finds that US monetary tightening depresses commodity prices. The source of the rate move is therefore essential to the interpretation. 5
A note on semiconductors
All eight semiconductor stocks in the sample have positive two-year rate betas: the median estimate is +0.64% per +10 bp, compared with +0.14% over five years. Yet the additional explanatory power is modest (median two-year ΔR²: 0.76%). This historical association depends on the estimation window; it does not establish that semiconductor stocks hedge rising rates.
Conclusion
With the US five-year yield back above 5%, the clearest pattern appears in familiar rate-sensitive sectors: 71 of 75 real estate, utilities and telecom stocks have negative two-year rate betas. Their sector-median estimates are −0.49%, −0.35% and −0.33% per +10 bp, holding the market return constant.
Listed property stands out: LEG Immobilien, Vonovia and TAG Immobilien show estimated sensitivities close to −1% per +10 bp. For portfolio managers, the practical question is whether otherwise different holdings concentrate the same exposure to rates.
Discuss your portfolio’s macro exposures
Which apparently different holdings share the same sensitivity — and which exposures depend most on the estimation window? Sismo helps investment teams examine these questions at stock and portfolio level.
Get in touch for a demonstration using your investment universe.
Request a demo →Methodology. Sismo snapshot: 25 September 2026. ETF holdings proxy for the STOXX Europe 600: 604 stock rows in the source, 596 eligible for the two-year analysis, and 579 with the five years of stock-price history required for the common comparison sample. All reported counts, rankings, sector medians and quartiles use the 579-stock common sample. Daily stock-return regressions include an intercept, MSCI Europe returns and the daily change in the US five-year Treasury yield (in percentage points). Stock returns are in decimals and yield changes in percentage points: +10 bp = 0.10, so beta × 10 gives the estimated percentage return component per +10 bp. Two- and five-year windows overlap. Sector figures are unweighted medians of stock-level metrics, not sector-portfolio regressions. ΔR² = R²(index + yield change) − R²(index only), using the same observations. It is reported as a percentage: 0.0878 = 8.78% of total return variance additionally explained (equivalently, 8.78 percentage points of R²). It is not the relative percentage increase in R², a share of residual variance, or a measure of statistical significance or stability. These conditional historical estimates are not causal effects or forecasts and do not measure the rate exposure already captured through the index. No portfolio weights are used. The illustrated grid is reconstructed from Sismo’s double-quartile view, rather than a product screenshot. Quartile boundaries include the 579 stocks and 33 sector medians. Tiles within each cell are arranged by ΔR², so their exact positions inside a cell do not encode beta magnitudes. Numbered sector markers are placed for readability within their correct quartile cells.
Sources. Sismo, analysis dated 25 September 2026. US five-year yield: Federal Reserve H.15 via FRED, DGS5, 4.99% on 23 September 2026 and 5.03% on 24 September 2026. These dates refer to daily observations, not to the first intraday crossing of 5%. The previous daily observation above 5% was 13 July 2007.
Research and company references. Research and company disclosures provide context for the mechanisms discussed above. They do not independently validate the estimated US five-year yield betas. All stock sensitivities and ΔR² values are calculated from Sismo data.
- Niels Joachim Gormsen and Eben Lazarus, Interest Rates and Equity Valuations, July 2025. Working paper, publicly hosted by the ECB.
- European Central Bank, Financial Stability Review, May 2026, sections 1.5 and 3.1–3.2.
- National Grid, FY2025/26 Full Year Results Statement, “Macro resilience”, p. 10.
- Cellnex, FY2025 results, 27 February 2026, debt profile and refinancing.
- IMF Working Paper 2023/215, Monetary Policy Transmission through Commodity Prices, 10 October 2023.