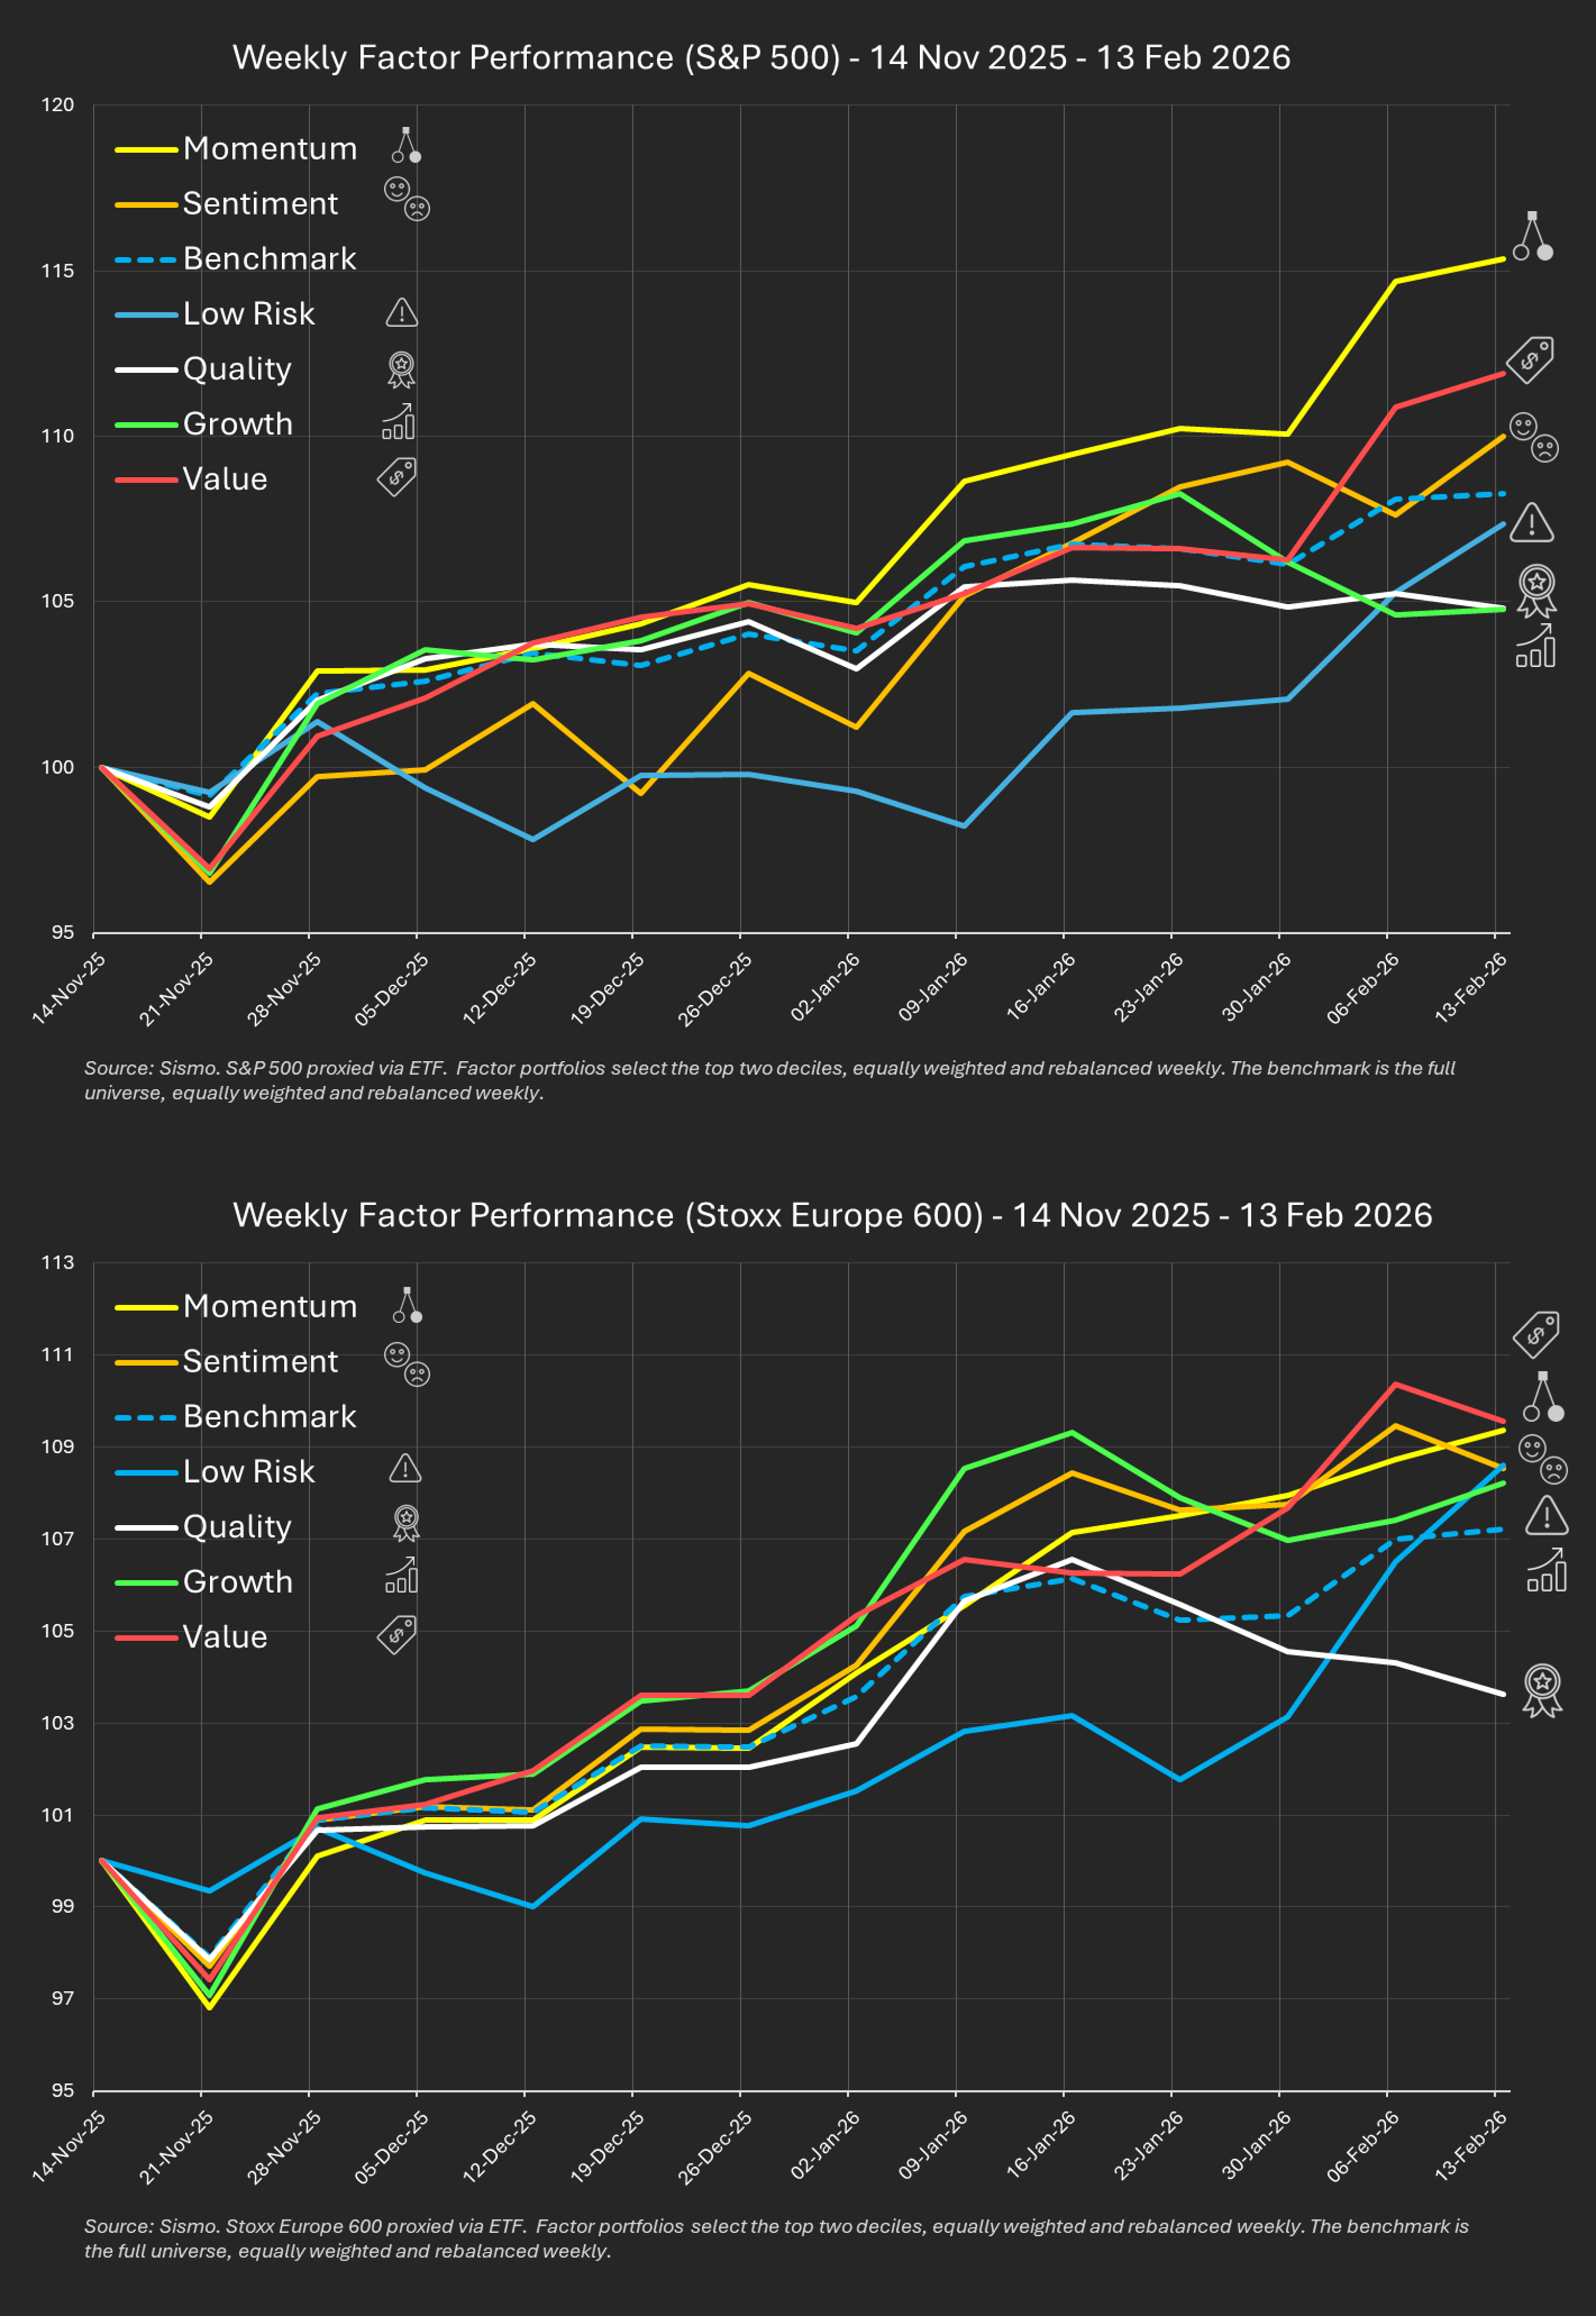
Since late December, relative factor leadership has strengthened rather than reversed.
We analysed weekly rebalanced top 20% factor baskets (equal-weighted) across:
Benchmarks are the full proxy universes themselves, also equal-weighted and weekly rebalanced.
This highlights relative performance across stocks - not index concentration effects.
Dispersion between factor leaders and laggards reached ~10 points.
The widening accelerated from early January - during earnings season.
There was no broad factor reset.
Relative trends strengthened.
Europe appears more balanced.
The US shows more concentrated leadership.
This period has been highly selective.
Certain industries - notably Software, repricing on AI-related competitive pressure - have been sharply penalised. Others have continued trending strongly.
At the factor level:
This does not look like a macro-driven regime shift.
It looks more like a reinforcement phase - where earnings season confirmed relative positioning rather than disrupting it.